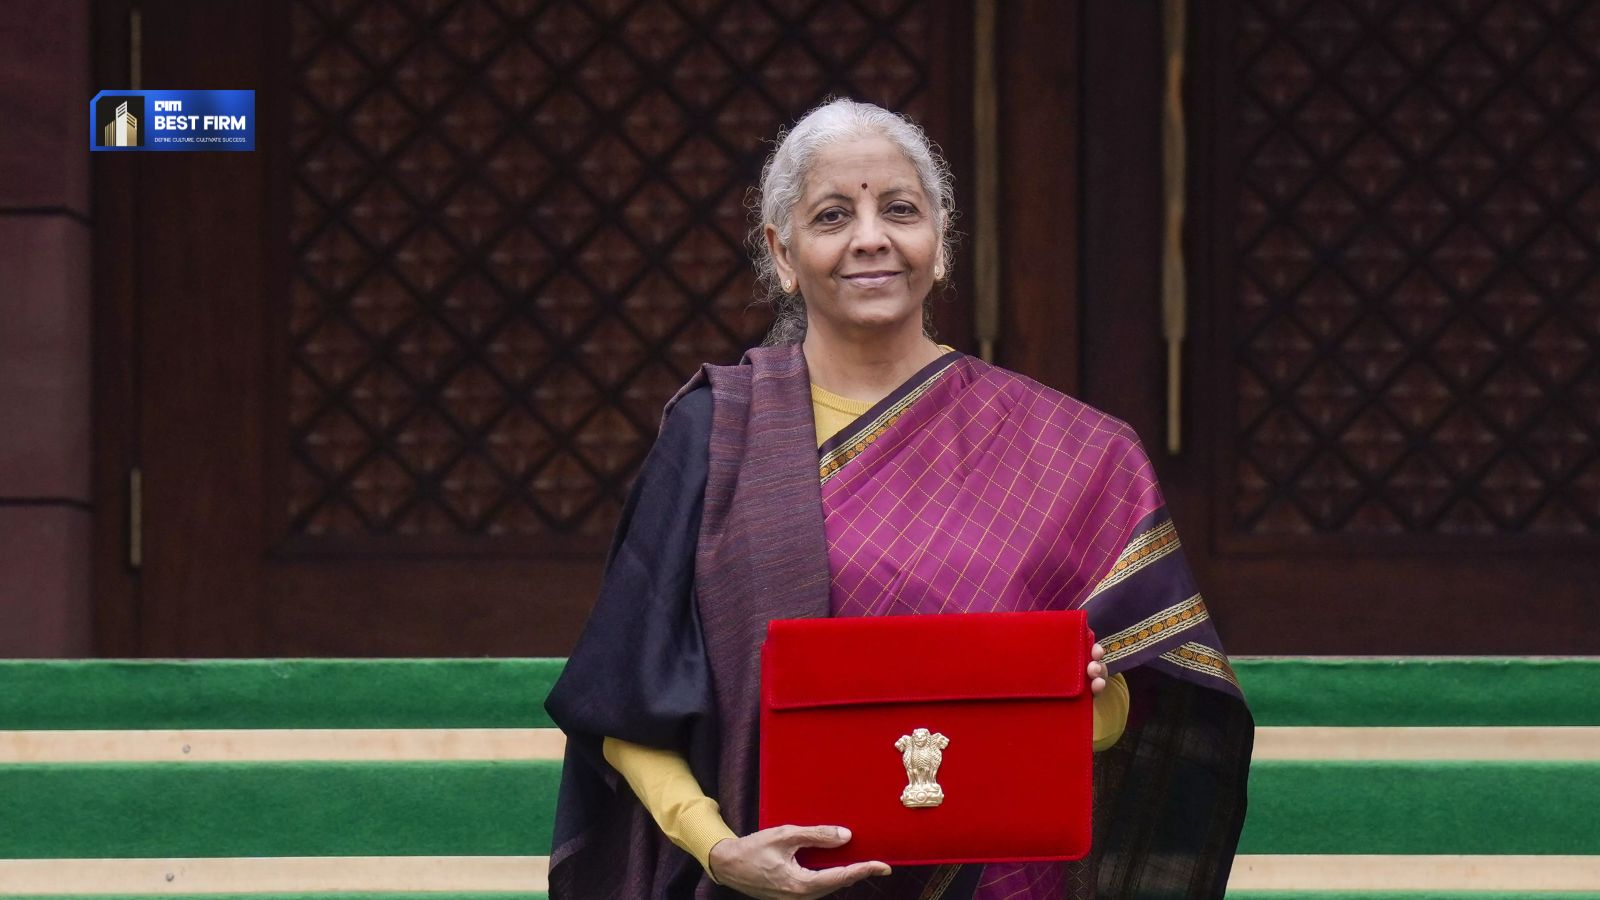
Union Budget 2026 Brings Key Changes for Employees, Employers and HR Leaders
The 2026–27 Union proposals, presented by Finance Minister Nirmala Sitharaman on February 1, introduce changes affecting income tax, payroll compliance, and workforce skilling for employees, employers, and HR leaders. Several announcements addressed long-standing procedural issues in income tax, contractor payments and employee-linked remittances.
In contrast to the past two years, when changes primarily involved incremental TDS adjustments and small-scale skilling initiatives, the 2026 measures focus on actionable processes and clear operational impact. This year’s proposals are unusually practical, almost demanding that HR and payroll functions rethink how they operate.
Unlike prior budgets, which largely tinkered at the edges, the 2026 measures give organisations tools to cut friction, improve compliance, and structure workforce strategy more confidently. However, the effectiveness of these measures will depend heavily on organisations’ internal readiness, which is uneven across sectors.
For HR teams, payroll managers, and business leaders, these proposals require system updates, policy adjustments, and active engagement with government-backed training programmes.
Many of the measures announced will take effect from the next financial year, with additional changes linked to the rollout of the Income Tax Act, 2025, from April 2026. The timing is important because organisations that do not act now could face operational disruptions when the new Act comes into force, especially in payroll processing and contractor classification.
Tax, Payroll and Compliance Changes That Matter at Work
One of the most immediate changes for employees is the extension of the timeline for revising income tax returns to March 31 following the end of the assessment year, replacing the December 31 deadline from 2025. Salaried individuals and professionals now have additional time to correct filing errors, update income details, and reconcile with information received after initial submission. The extended timeline adds nearly three months compared with last year, making it easier for payroll and finance teams to manage end-of-year reconciliations.
The proposals also revised the Tax Collected at Source under the Liberalised Remittance Scheme (LRS). TCS on overseas remittances for education and medical treatment has been reduced to 2% from 5% in 2025, while TCS on overseas tour packages is now 2% without any threshold. Compared with the 2024–25 adjustment, this is a more substantial easing of the upfront tax burden for employees and families, which will help to streamline overseas payments. This is arguably one of the most tangible benefits for employees in recent budgets, offering measurable relief rather than theoretical compliance improvements.
Employers received clarification on tax deduction at source for manpower supply services. Payments for manpower supply will now be treated as contractor payments for TDS purposes, with a uniform rate of 1% for individual contractors and 2% for others. In previous years, payroll and finance teams faced uncertainty over classification, leading to conservative practices and additional compliance checks. The 2026 clarification reduces ambiguity and administrative burden. The clarity here could also influence hiring practices and outsourcing decisions, giving companies greater confidence in workforce structuring.
Another compliance-related measure relevant to payroll administration is the proposed automation of lower or nil TDS certificates. Eligible taxpayers will be able to obtain such certificates through a system-driven process rather than manual approvals. Employers implementing payroll deductions will need to align internal systems once the detailed guidelines are issued. From an operational standpoint, this could eliminate weeks of manual paperwork for HR and finance teams, which in itself is a productivity gain that many previous budgets promised but never delivered.
The Budget also confirmed that the Income Tax Act, 2025, will come into force from April 1, 2026. The new law consolidates multiple provisions of the existing tax framework and introduces changes to return formats, procedural timelines and compliance workflows. HR and payroll teams will need to prepare for these changes during the transition period.
Skilling Push and Employment-Linked Programmes
Skilling and employability received one of the largest funding increases in recent years, rising to ₹9,886 crore in 2026–27 from ₹6,100 crore in 2025–26 and ₹4,500 crore in 2024–25. Whereas earlier budgets focused on pilot programmes and infrastructure upgrades, the 2026 allocation for the Ministry of Skill Development and Entrepreneurship supports structured, large-scale training and job-linked skilling programmes across sectors. While the scale is impressive, the allocation still leaves gaps in regional access and emerging skill needs that the market will need to address separately.
A major component of this allocation is the expansion of the PM SETU programme aimed at upgrading Industrial Training Institutes. The initiative focuses on modernising infrastructure, revising curricula and strengthening industry participation in training delivery and assessment. Compared with 2024, this moves beyond simple facility upgrades to actively shaping employable skills.
Healthcare and care services also featured prominently in the skilling announcements. The Budget outlined a plan to train 1.5 lakh caregivers in areas such as elder care, disability support and allied health services. Alongside this, the government plans to expand Allied Health Professional institutions to add training capacity for an additional 100,000 workers over the next five years. These measures address workforce demand in care-related roles across public and private settings and also show a significant scale-up from 2025, when approximately ₹4000 crore was allocated for health-skilling initiatives.
Tourism-linked employment received targeted attention through a pilot programme to train 10,000 tourist guides across key destinations. This is a substantial increase from 2024 initiatives, which trained around 2,000 participants regionally. The training will follow a 12-week hybrid format and will be developed in collaboration with the Indian Institute of Management.
The government also announced support for short-duration professional skill courses designed by statutory bodies such as the Institute of Chartered Accountants of India and the Institute of Company Secretaries of India. These modular courses are intended to strengthen employability for graduates and early-career professionals entering finance, accounting and corporate governance roles.
What HR Leaders Need to Act On
For HR leaders, the 2026 measures combine compliance adjustments and workforce development initiatives that require operational planning. The extended return revision window, clarified TDS treatment for manpower supply, and automation of certificates will require updates to payroll systems, vendor contracts, and employee tax support mechanisms.
The implementation of the Income Tax Act, 2025, from April 2026 adds another layer of preparation for HR and finance teams. Organisations will need to review payroll structures, internal policies and employee communication plans to ensure alignment with revised procedures and reporting requirements.
The increased allocation for skilling also creates opportunities for employer participation. With higher public funding for vocational and professional training, HR teams may evaluate partnerships with Industrial Training Institutes, training providers and government-supported programmes to address skill gaps and improve hiring pipelines. Engagement with sector-specific skilling initiatives may become more relevant for organisations facing talent shortages.
Union Budget 2026 focuses on administrative clarity, training capacity and procedural improvements rather than changes to employment law. For employees, employers and HR leaders, the key takeaways lie in how these measures affect payroll compliance, employee tax experience and access to job-linked skilling during the upcoming financial year.
About Mansi Mistri
Mansi is a writer who enjoys breaking down complex topics into simple, readable stories. She is curious about how ideas move through people, platforms, and everyday conversations. You can reach out to her at [email protected].